As the UK prepares to introduce a carbon price on imports of cement and hydrogen from January 2027, two companies emerging from the Carbon13 venture builder are developing cleaner industrial alternatives designed to compete on cost.
For much of the past decade, choosing a cleaner industrial product has often meant paying more. Green hydrogen has typically cost more than hydrogen produced from natural gas, while low-carbon cement has remained more expensive than conventional Portland cement.
Known as the **green premium**, the price difference has been one of the major obstacles to industrial decarbonisation. Companies may want to reduce their emissions, but many continue to choose cheaper, higher-carbon alternatives.
That equation could now be changingFrom 1 January 2027, the UK’s Carbon Border Adjustment Mechanism (CBAM) is expected to place a carbon price on imports in sectors including cement and hydrogen, increasing the cost of carbon-intensive products entering the country.
At the same time, a growing number of start-ups are attempting to reduce the cost of producing cleaner alternatives.
Two companies being backed and researched by SyndicateRoom, which manages SEIS funds investing in businesses from the Carbon13 venture builder, illustrate this emerging approach: Ki 13 and Cocoon
Ki 13 was formed through the Carbon13 venture-building programme, where Koji Muto, a former hydrogen specialist at ExxonMobil, met Cambridge physics PhD Michael Stanton. Carbon13 backed the company in 2023.
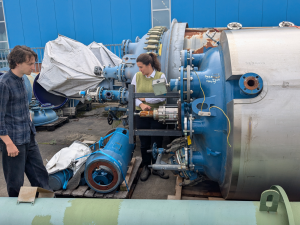
Rather than producing hydrogen through conventional water electrolysis, Ki 13 uses an electrochemical process to split biomass, including wood chips and agricultural residues, to produce hydrogen.
The company reports that its process requires around **25 kWh of electricity per kilogram of hydrogen**, approximately half the energy required by conventional water electrolysis. This is significant because electricity is one of the largest costs associated with hydrogen production.
The process also produces biogenic carbon dioxide, potentially providing e-fuel producers with two of the key feedstocks needed for synthetic fuels from a single production process.
In September, Ki 13 announced a $5 million seed round led by HICO Investment Group. The company also reports more than $15 million in annual recurring revenue represented by signed letters of intent with European e-fuels producers** and is developing a pilot plant in West London.
“The world needs a radical cost difference in how synthetic fuels and chemicals are made to drive the transition at scale and at pace,” said Koji Muto, co-founder and CEO of Ki 13.
Cocoon was formed at Carbon13 in 2023 by Eliot Brooks, Dr Will Knapp and Freddie Scott.
The company takes slag generated by electric arc steel furnaces—traditionally treated as a waste product—and processes it into **LoopCem**, a material that can replace a portion of the cement used in concrete.
According to the company, LoopCem can reduce the embodied carbon of concrete by up to **40%** while matching the performance of the materials it replaces.
The opportunity is significant. Cement production is responsible for approximately 8% of global CO₂ emissions, according to the World Economic Forum.
Cocoon raised $15 million in a Series A round in March 2026, co-led by 2150 and Brick & Mortar Ventures. The funding will support the construction of its first commercial demonstration facility in the United States.
“We’re focused on delivering a plug-and-play solution that gives concrete producers access to affordable, local materials—while improving the economics of electric steelmaking,” said Eliot Brooks, CEO of Cocoon. “Expanding supply is the fastest way to stabilise costs and lower carbon in concrete.”
For years, the argument for industrial decarbonisation has often rested on environmental responsibility. But businesses ultimately have to consider their costs, competitiveness and profitability.
Tom Britton, Partner at SyndicateRoom, argues that the green premium cannot be relied upon as a permanent feature of the transition.
“The green premium has been treated as a fact of life, the price of having a conscience,” he said. “That was never going to scale. Nobody converts a cement works or a refinery out of goodwill. They switch when the clean option is cheaper or better.”
For Britton, the significance of Ki 13 and Cocoon is that both companies are attempting to eliminate the need for customers to pay a premium for choosing lower-carbon products.
Nicky Dee, CEO of Carbon13, said the companies demonstrate how ventures emerging from its programme are working to reduce the cost of sustainable industrial production and accelerate the transition to a lower-carbon economy.
The combination of carbon pricing, technological innovation and pressure to reduce industrial emissions** could reshape the economics of some of the world’s most carbon-intensive industries.
If companies such as Ki 13 and Cocoon can demonstrate that cleaner industrial products can compete with—and potentially outperform—conventional alternatives on cost, the green premium may gradually cease to be a barrier to decarbonisation.
The bigger question is whether these technologies can scale quickly enough to meet the demands of global industry.